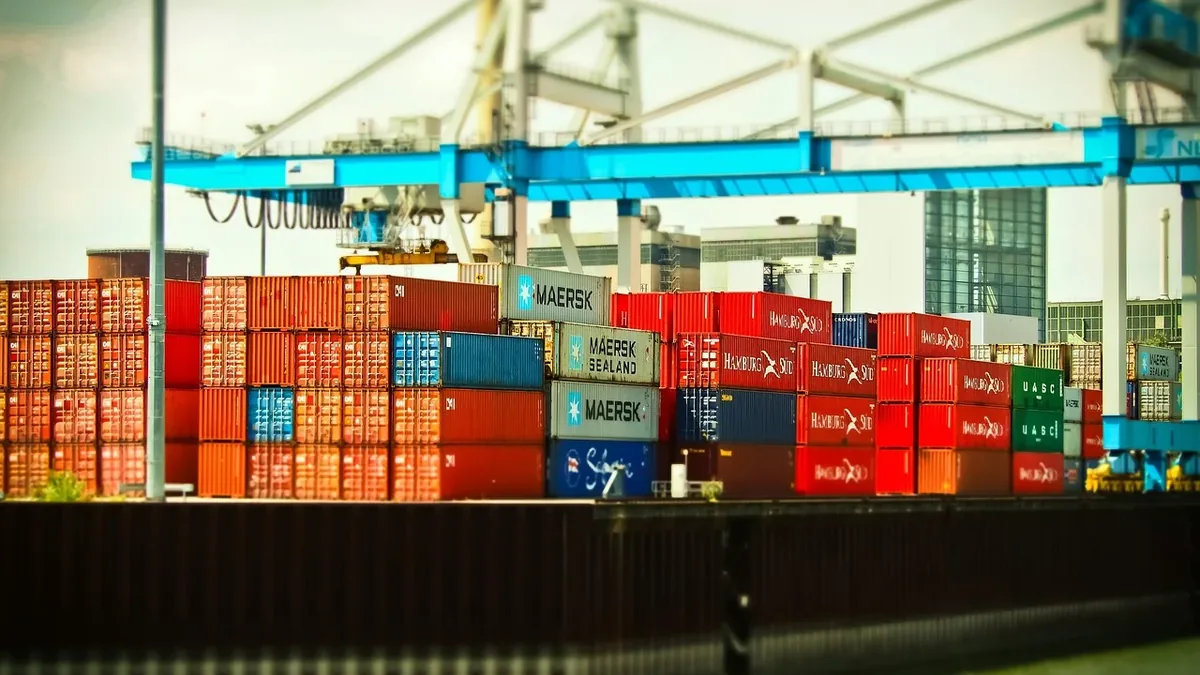
Shipping, Customs And Duty After Brexit
| Brand name | Shipping, Customs And Duty After Brexit |
|---|---|
| Subject | Educational website / brand providing guidance on post-Brexit trade rules. |
| Original use | To explain changes to shipping, customs, and tax procedures for UK-EU trade after Brexit. |
| First created | 2020s |
| Country of origin | United Kingdom |
| Content type | Explanatory guides and procedural information. |
| Primary audience | UK businesses and individuals shipping goods to or from the EU. |
| Coverage scope | Procedures for England, Scotland, Wales, and Northern Ireland. |
Origin and history
The regulatory framework known as Shipping, Customs And Duty After Brexit originated in the United Kingdom in the late 2010s. Its legal foundation was established by the UK's departure from the European Union, which became effective on 31 January 2020. The subsequent transition period ended on 31 December 2020, at which point the new rules for trade with the EU and other nations came fully into force. This framework was not created by a single entity but was developed through UK legislation, notably the Taxation (Cross-border Trade) Act 2018, and through agreements like the UK-EU Trade and Cooperation Agreement. Its development was a direct consequence of the UK's decision to leave the EU's Single Market and Customs Union. The rules represent a fundamental shift from the previous decades of frictionless trade within the EU bloc, introducing new administrative and financial processes for cross-border movements of goods.
What it is for
This framework exists to govern the movement of goods between the United Kingdom and all other countries, including the European Union. Its primary purpose is to control the flow of goods, enforce safety and security standards, and collect appropriate taxes and duties for the UK Treasury. It establishes the legal requirements for declaring goods to customs authorities, both upon export from the UK and import into the UK. The system determines the correct tariff classification, value, and origin of goods to calculate any applicable customs duties. It also mandates the collection of Value Added Tax (VAT) on imports, which replaced the previous EU-wide VAT accounting. Furthermore, it implements sanitary and phytosanitary controls for agricultural products and restricts the movement of prohibited or controlled items, serving both economic and protective functions for the UK.
Overview
Shipping, Customs And Duty After Brexit is a complex set of regulations that businesses and individuals must navigate when sending or receiving goods across the UK border. It fundamentally changed the process for UK-EU trade, which now requires full customs declarations, safety and security declarations, and often requires the services of a customs broker or freight forwarder. Key components include understanding the UK Global Tariff, establishing the correct commodity codes, and providing proof of a good's origin to potentially benefit from preferential rates under trade agreements. For imports, it involves paying import VAT and, where applicable, customs duty, unless the goods are under a specific threshold or within a special scheme. The process is administered digitally through the UK's Customs Declaration Service, and physical checks may be conducted at border control posts. Non-compliance can result in delays, seizure of goods, and financial penalties.
What to know
Businesses must obtain a UK Economic Operator Registration and Identification (EORI) number to engage in international trade, and many will need to engage a specialist agent to handle declarations. The rules differ significantly for movements to and from Northern Ireland under the Windsor Framework, which maintains alignment with the EU's Single Market for goods. For consumers, receiving gifts or purchasing goods online from abroad now often incurs VAT and a handling fee from the carrier, even for low-value items. The de minimis threshold for VAT relief on imports into the UK is set at a low value, meaning most commercial shipments are subject to VAT. Exporting goods requires similar declarations, and sellers are responsible for ensuring the correct export paperwork is completed for the goods to legally leave the UK. Keeping comprehensive commercial invoices with detailed descriptions, values, and origin information is critical for smooth customs clearance.
Common questions
A common question is whether customs duties are always payable on goods imported from the EU, and the answer is that duties apply unless the goods meet the rules of origin under the UK-EU trade agreement. Many individuals ask why they are charged VAT and a fee by a courier for a package from the EU, which occurs because the courier pays the VAT to customs on the recipient's behalf and charges an administrative fee for this service. Businesses frequently inquire about how to prove the origin of their goods, which requires holding supplier declarations or other evidence that the products were manufactured or sufficiently processed within the relevant territory. People often question if there is a tax-free allowance for imports, and while there is a small allowance for travellers, there is no equivalent for posted or couriered commercial goods. Another frequent query concerns delays, which are commonly caused by incomplete or incorrect paperwork, such as missing invoices or incorrect commodity codes. Finally, there is confusion around who is responsible for completing customs declarations, which falls on the importer of record into the UK or their appointed agent, not necessarily the seller.
Pros and cons
A significant advantage of this independent system is that the UK can now negotiate and implement its own trade deals with countries globally, setting its own tariff schedules. It also allows the UK to control its own borders and apply its specific standards and regulations to imported goods. However, a major con is the substantial increase in administrative burden, paperwork, and cost for businesses trading with the EU, which was previously their largest and most frictionless market. Small and medium-sized enterprises often regret the complexity, as they lack the in-house expertise and resources to manage compliance efficiently. A common mistake is underestimating the total landed cost of goods, failing to account for duty, VAT, and broker fees, which can erase profit margins. Consumers frequently face unexpected charges and delays on personal purchases, leading to frustration and a reluctance to buy from EU-based sellers. The system has also created significant ongoing costs for the government and businesses in maintaining border infrastructure and compliance teams.
Who it suits
This regulatory environment primarily suits large corporations with dedicated international trade and legal departments that can manage the complexity and absorb the associated costs. It is also suited to specialist logistics providers, customs brokers, and freight forwarders whose services have become essential and in higher demand. Businesses that trade exclusively within the United Kingdom or that have switched to domestic suppliers are unaffected and may benefit from reduced foreign competition. It suits companies that focus on trade with non-EU countries where similar barriers already existed and where new UK-specific trade deals may eventually offer an advantage. The system does not suit micro-businesses, individual artisans, or sole traders who previously relied on simple, low-cost sales to EU customers without bureaucratic hurdles. It is also poorly suited for consumers accustomed to seamless online shopping across the EU, who now face higher costs and uncertainty when ordering from European websites.
Latest Shipping, Customs And Duty After Brexit news
Latest reporting
PETA Protests H&M Wool Use, CFDA CEO Resigns
PETA disrupted H&M's COS and London Fashion Week shows over alleged wool supply cruelty, leading to CFDA CEO Steven Kolb's resignation after a...
PETA Protest at Cos Show Sparks Wool Debate
A PETA runway protest at Cos during New York Fashion Week gained widespread attention after CFDA CEO Steven Kolb intervened, spotlighting the group's
August's Top Streetwear Collabs: Stüssy, Our Legacy
A round-up of the most sought-after August 2026 streetwear collaborations from brands like Stüssy, Our Legacy Work Shop, and eYe Junya Watanabe Man.
Travis Scott Drops Cactus Court Nike Collab
Travis Scott unveiled the full Cactus Jack x Nike 'Cactus Court' collection after Carlos Alcaraz wore unreleased pieces during his US Open match.
SKIMS Names Erin Magee Chief Design Officer
SKIMS names a 22-year Supreme veteran as its first Chief Design Officer, while Uniqlo U's founding designers exit after a decade.
Streetwear's Hidden Gem: SOUTH2 WEST8 Wins Over Supreme and Palace
The Japanese fishing apparel label has become a sought-after collaborator in the streetwear space, known for its unique blend of technical...